It handily publishes totals of new borrowers in its scheme as at 31 October each year.
Of course not all students take out a loan – but the headline figures are good enough to give us a sense of what’s happening to home domiciled numbers overall.
First here’s England domiciled FT undergrads:
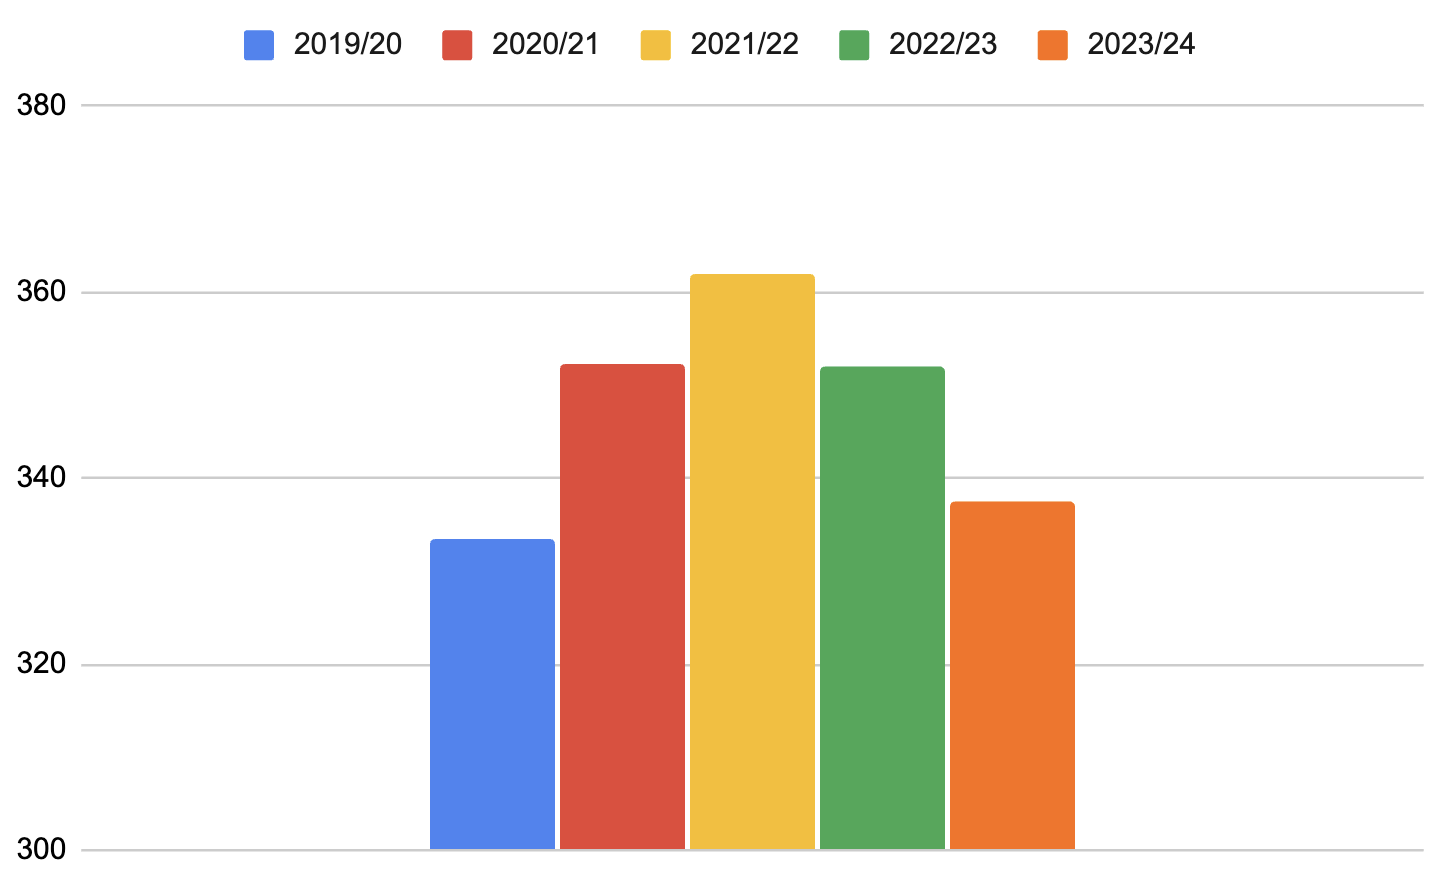
That initial rise in participation was widely put down to a lack of other opportunities in the labour market during the pandemic – but to be back roughly at 2019’s numbers now is extraordinary.
Are they switching to part-time? They are not:
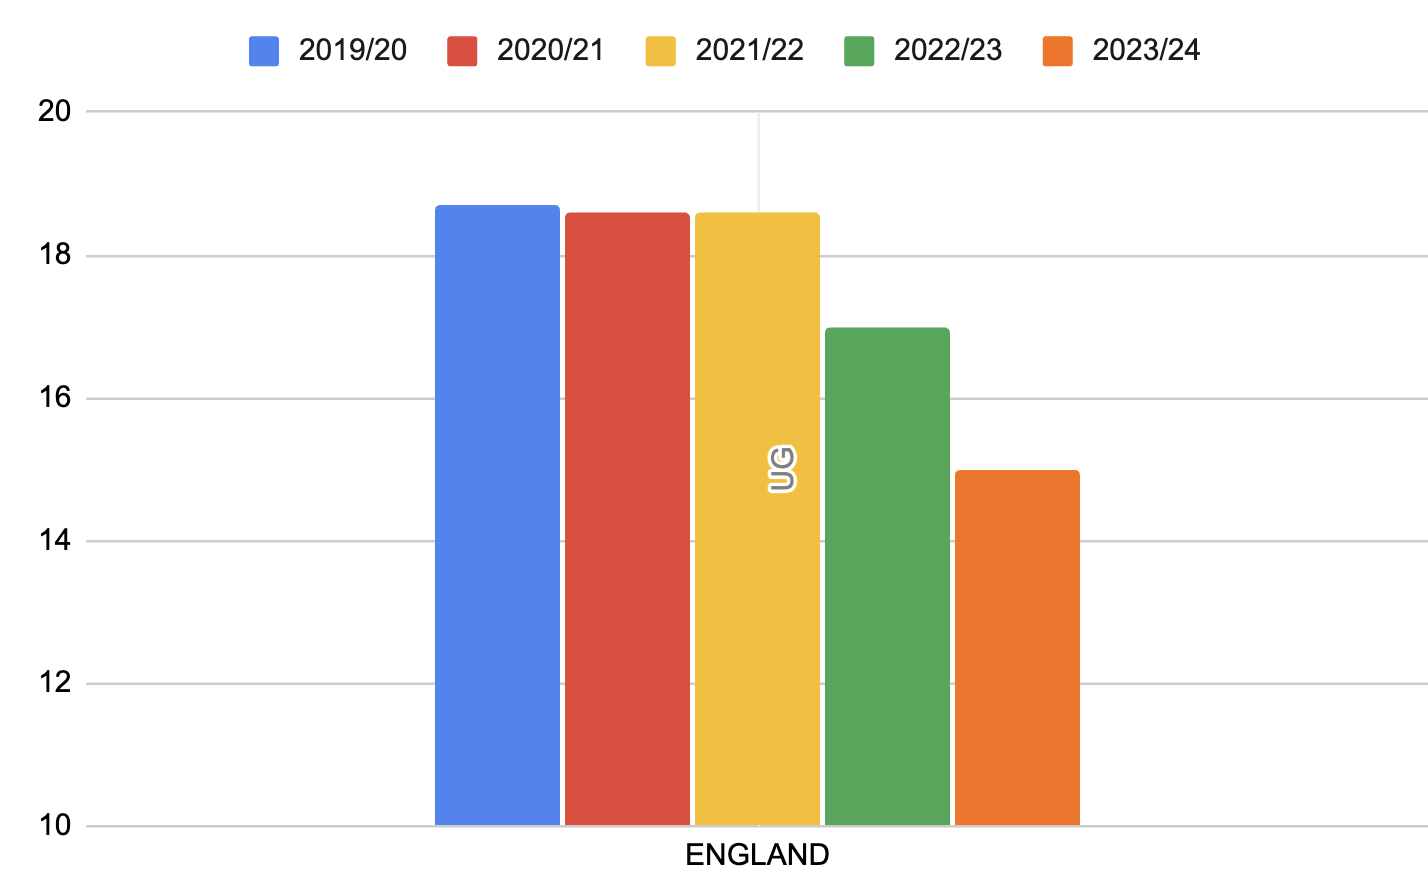
New PG borrowers are down too:
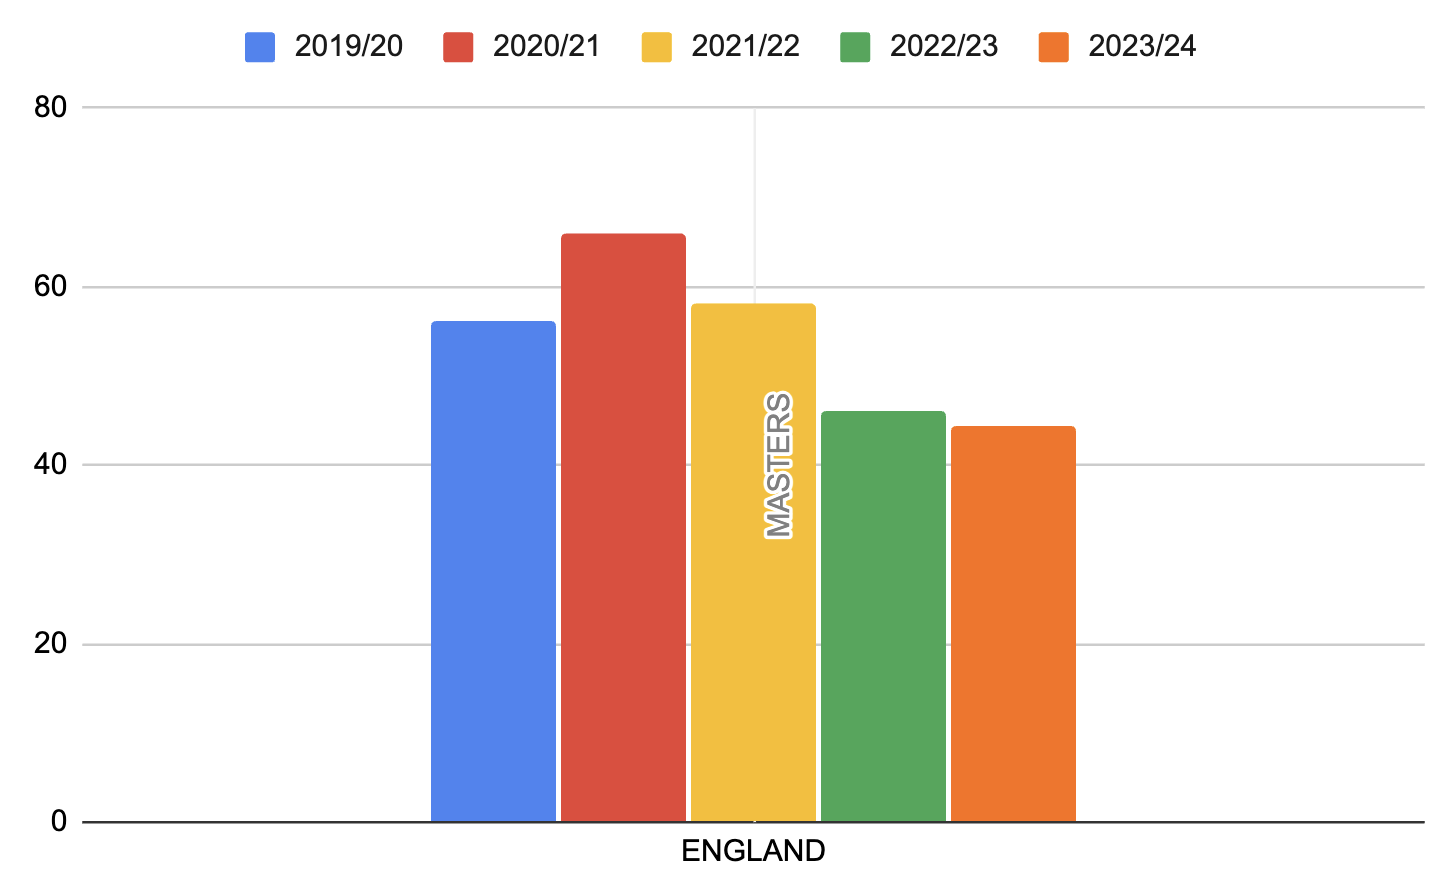
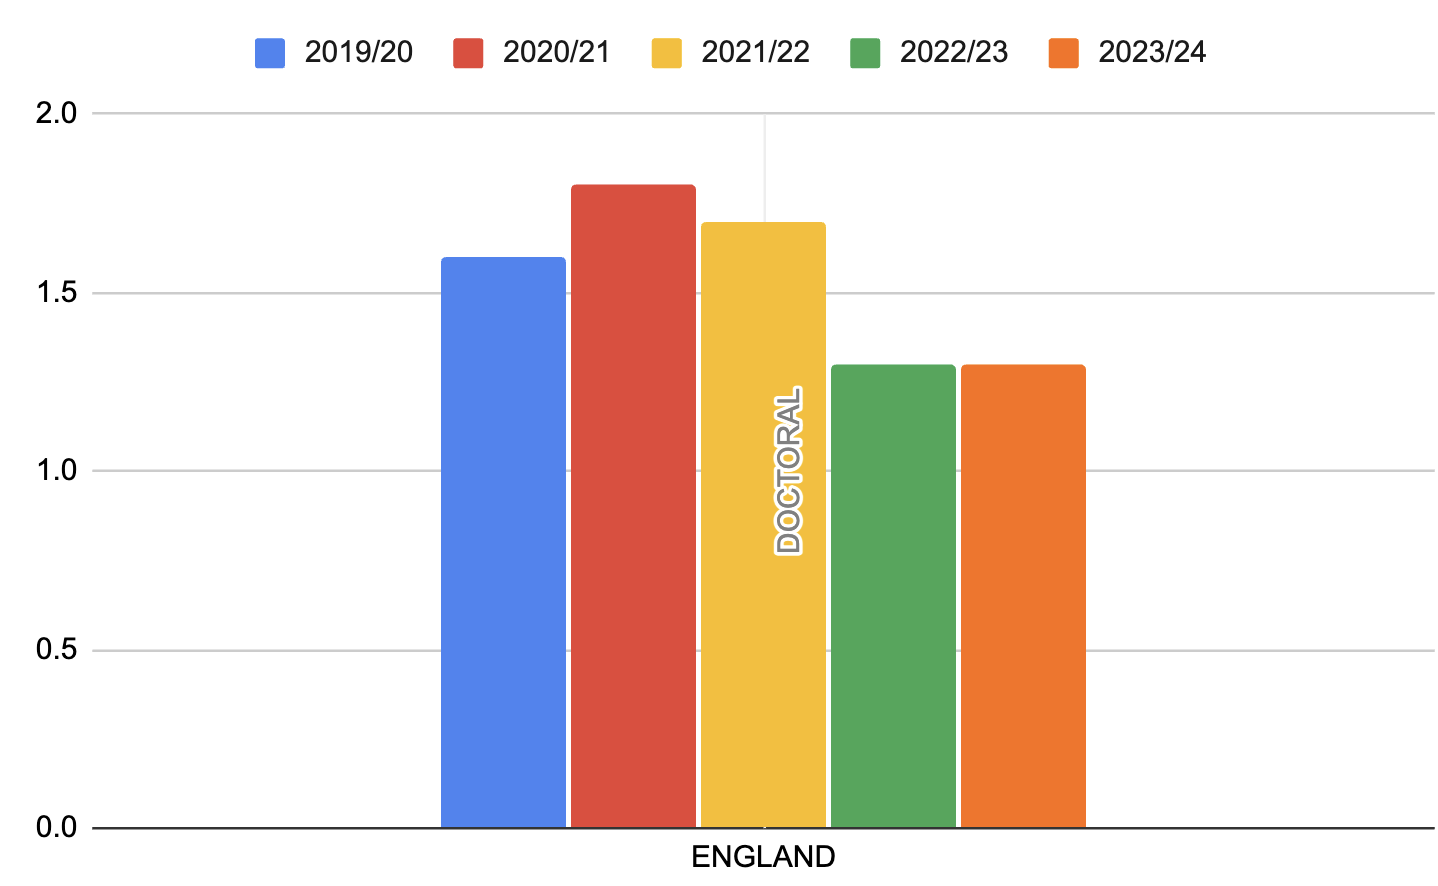
That’s all the more worrying given the previous increases in UG participation. And here’s what happening on new Doctoral borrowers:
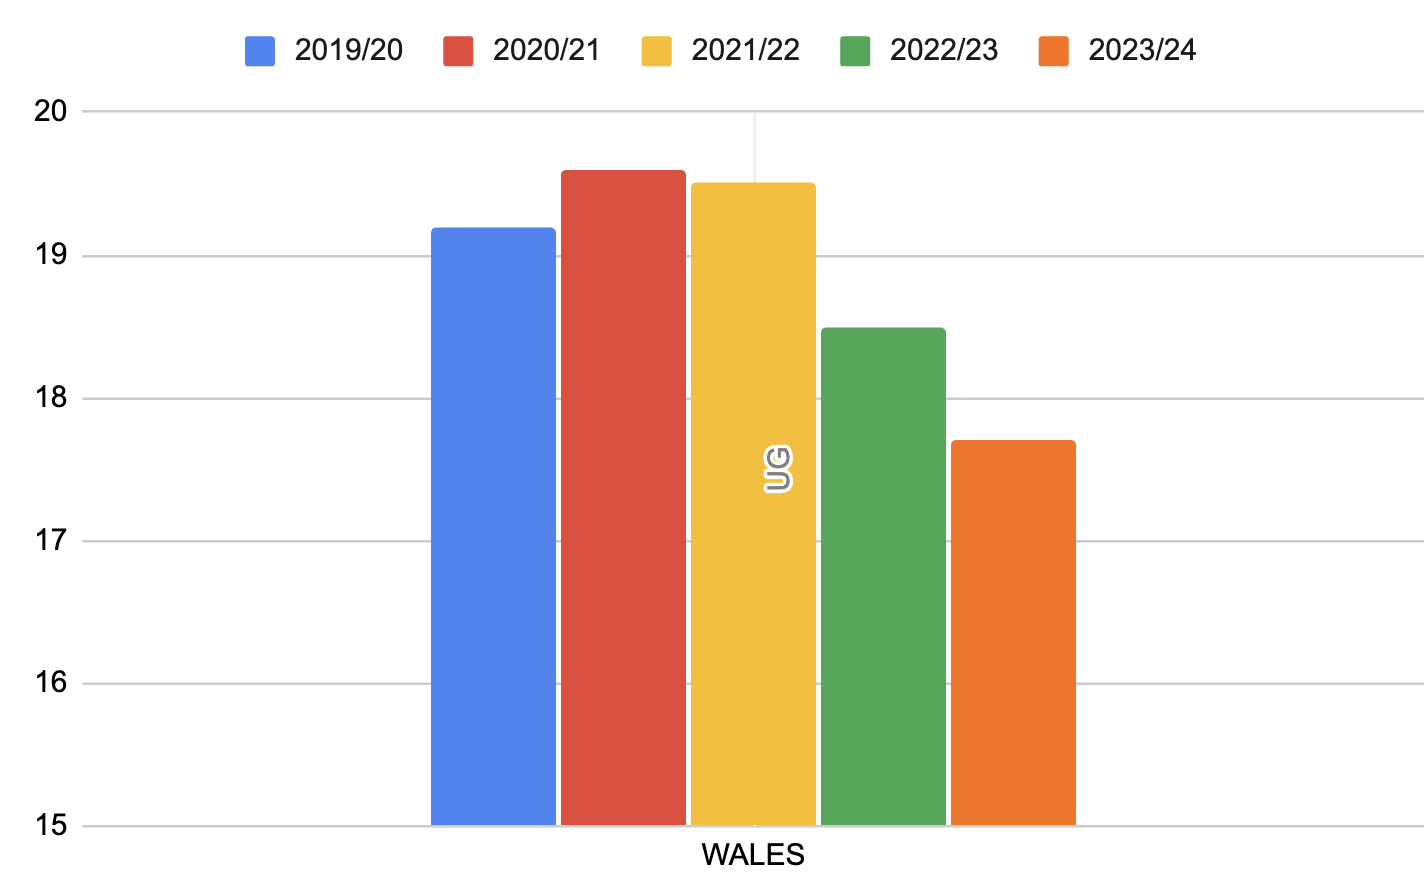
Are we seeing the same things for borrowers from Wales and NI? Sort of. Here’s Wales FT UG new borrowers – which looks worse than England’s decline:
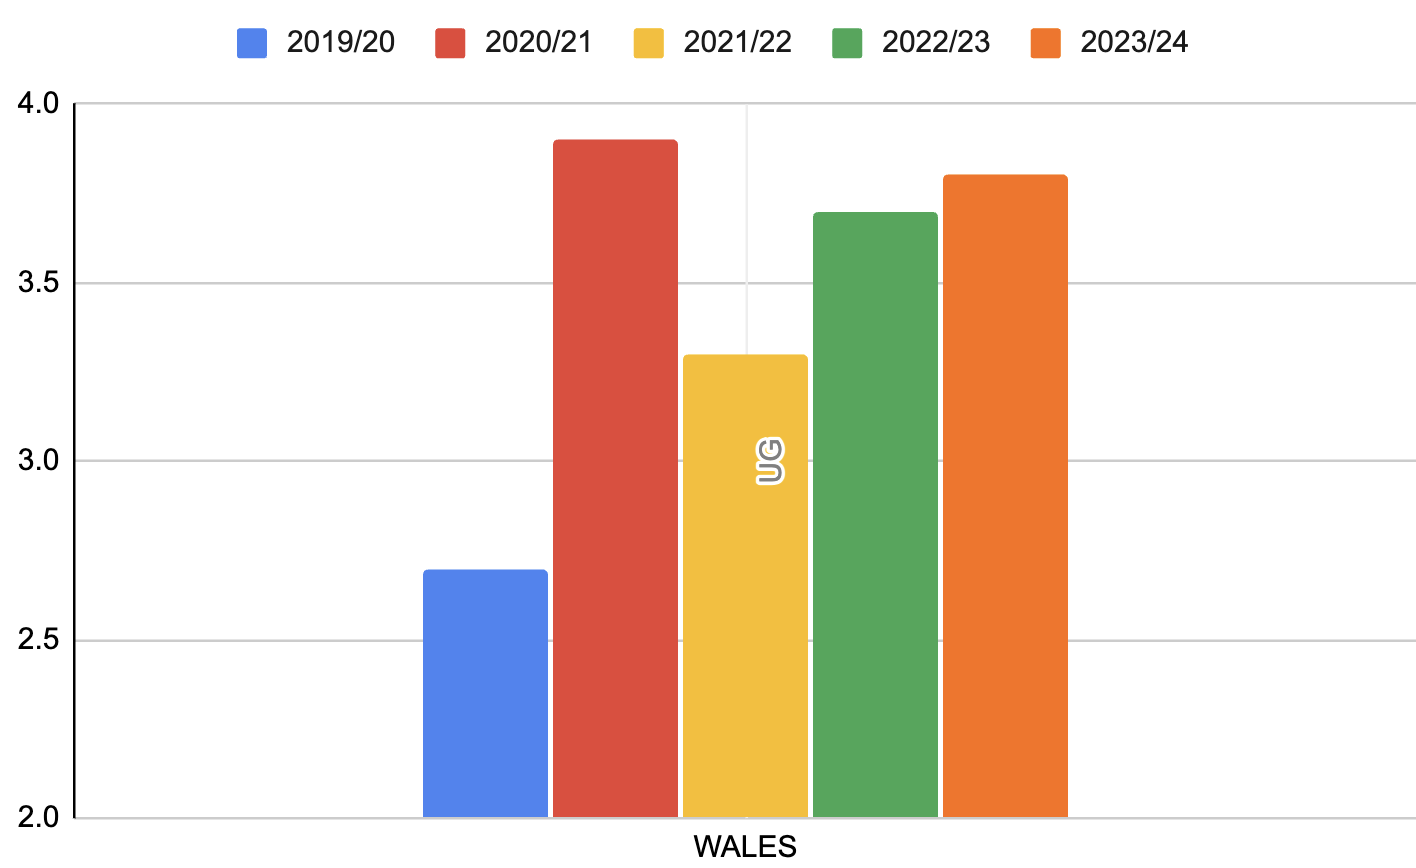
PT UG is actually up in Wales:
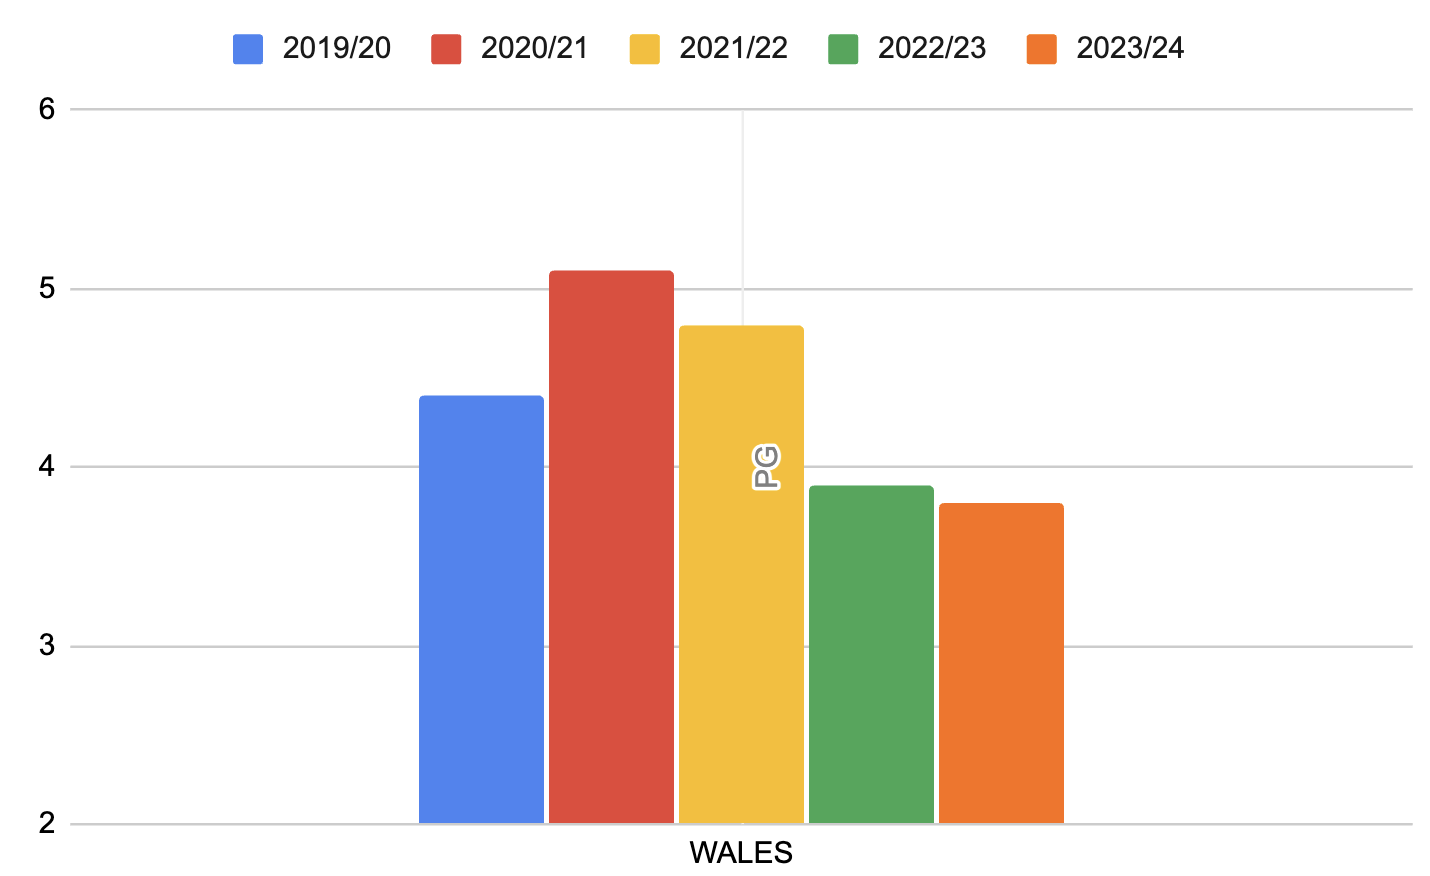
And Welsh PG loan take up has pretty much levelled off:
In Northern Ireland, FT UG numbers look to have levelled off too:
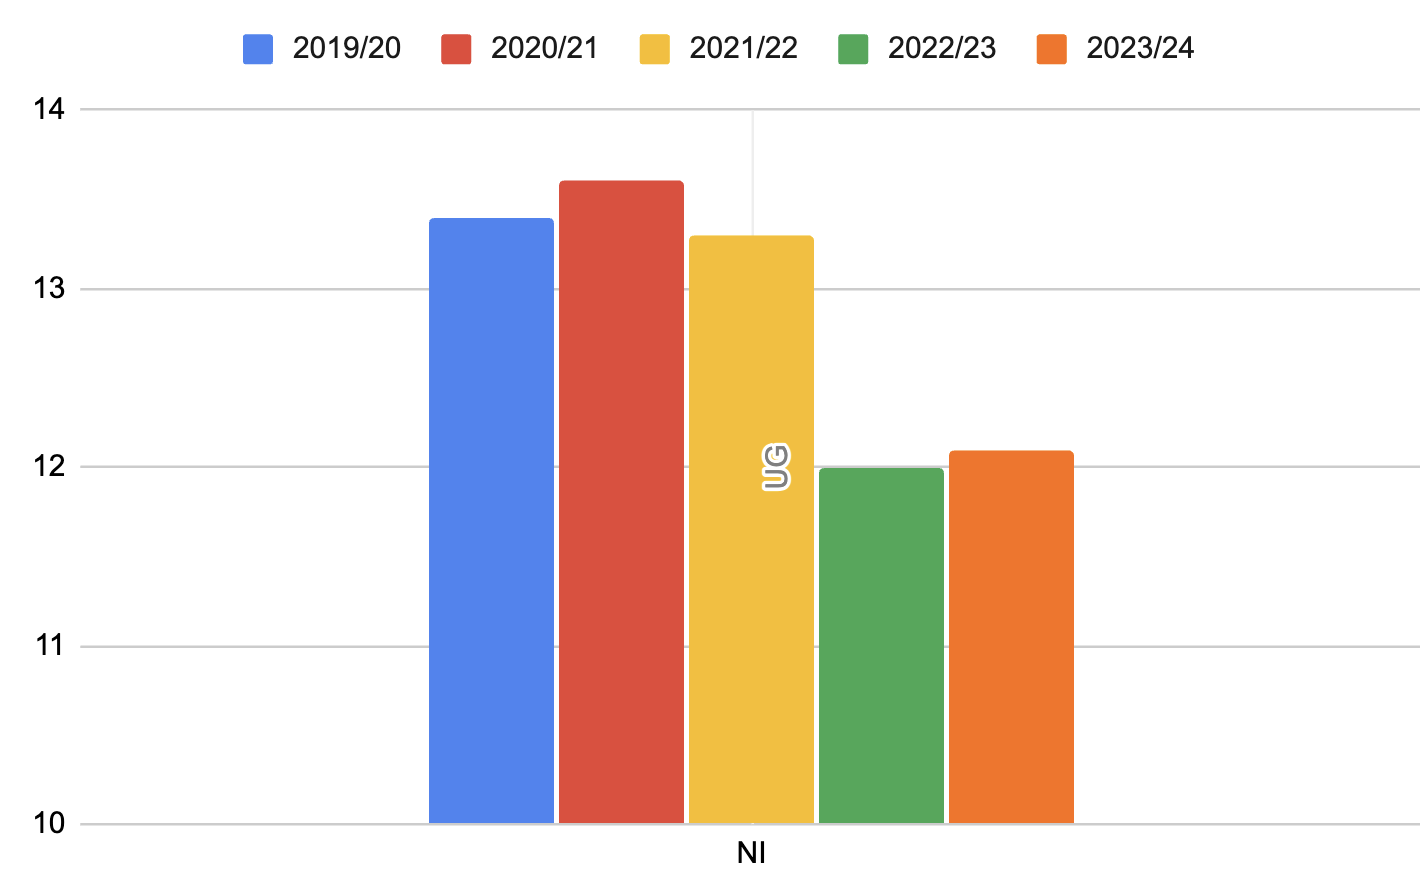
Underpinning all of that will be some of the pandemic bulge eating away at the pool of demand in future years, as well as the declining real-terms value of maintenance loans (even in Wales, where the non-means tested total package has been rising by wage growth but not inflation).
Here’s the average amount paid out in maintenance loans to FT UG borrowers in England. Remember this is not adjusted for inflation, and the package is supposed to rise with inflation – so the 2022/23 fall almost certainly a facet of “fiscal drag” in the means testing threshold:
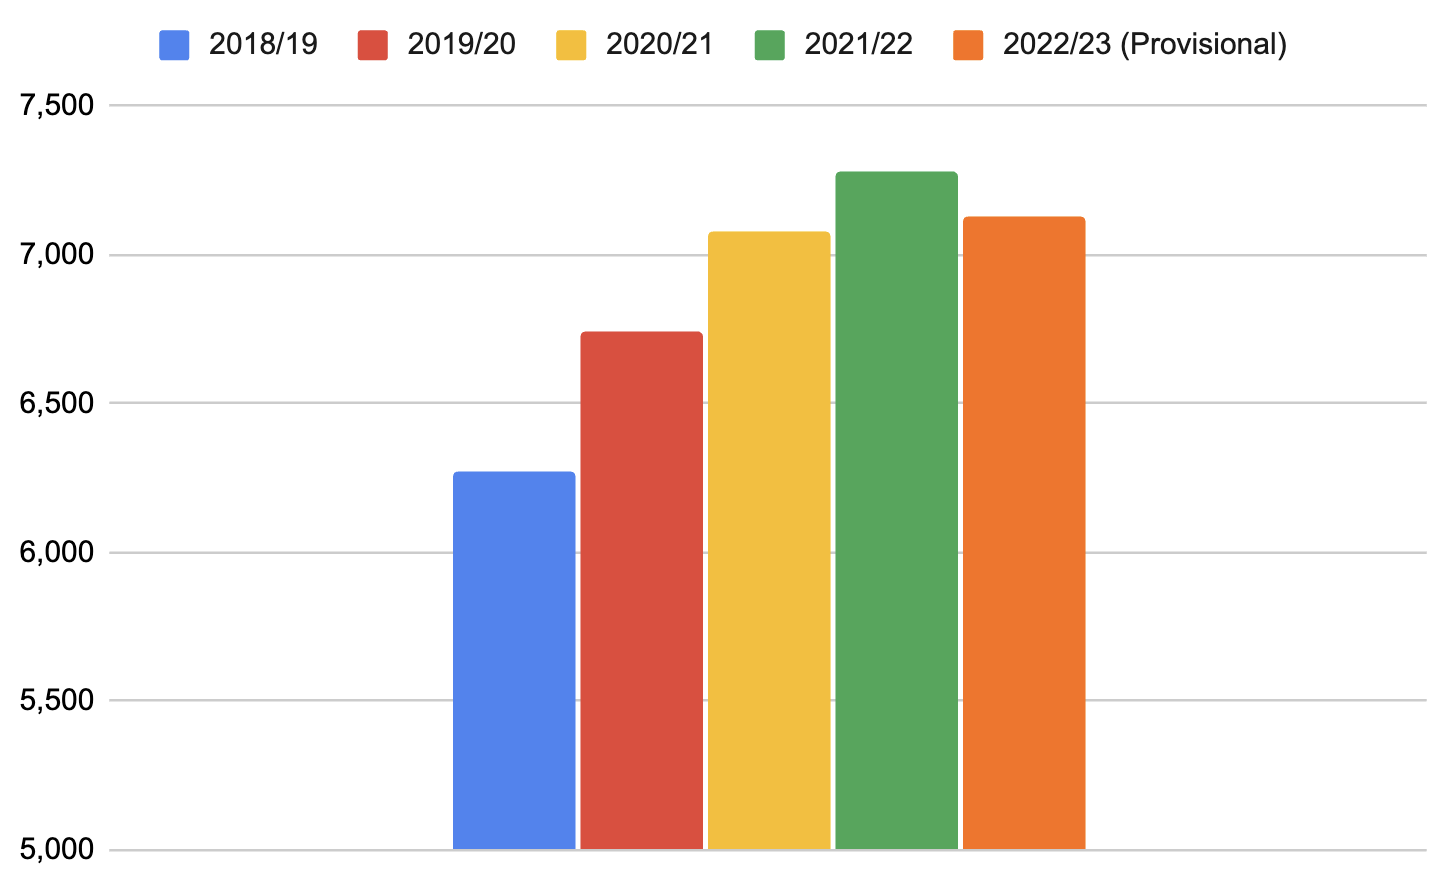
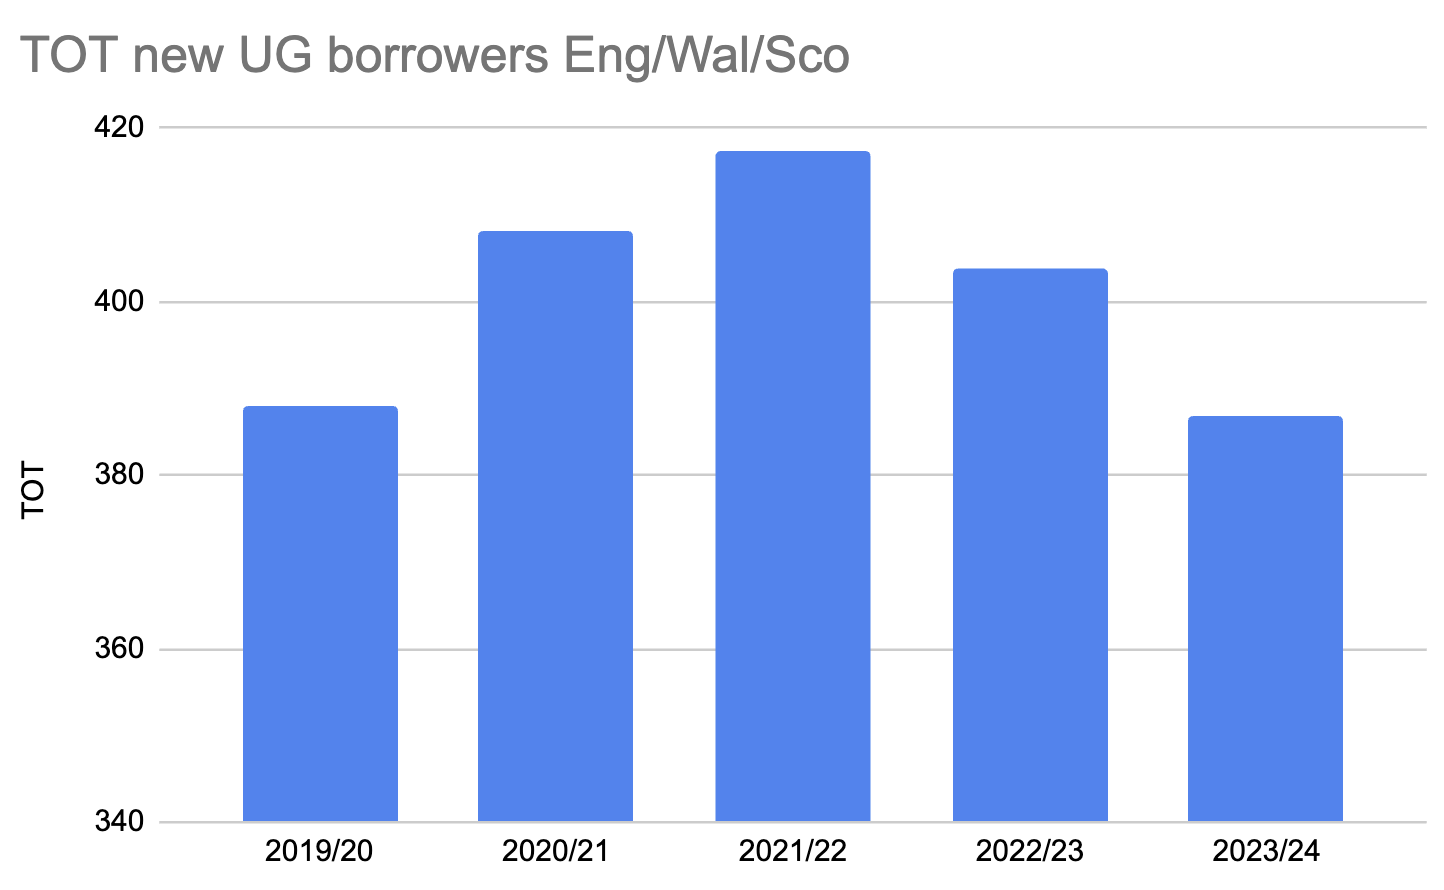
It certainly looks like student support’s failure to keep up with inflation is starting to bite. Here’s total new borrower UG loan take up across England, Wales and NI: